Engineering · 2026.09.30 · 6 min · Updated 2026.10.26
Should You Change a Trading Strategy While Losing? Coding the Review Process, and 13 Variants That Failed
I wrote 'reassess if losses persist' as preset triggers and a fixed decision order; the first automatic trigger caught two bugs in the review code, and none of 13 risk-reduction variants passed the preset bar.
Reading
When a trading strategy is actually losing, the thing you most want is to change parameters right away. I had coded my review process in advance, and the first time it fired, the report gave two wrong verdicts, both from bugs in the review code.
Once those were fixed, the verdict was normal volatility: keep the strategy.
The report also flagged a portfolio-level risk. I tested 13 ways to reduce it, and none passed the criteria I had set in advance.
This is a byproduct of my 1,000 USDT crypto trend strategy paper trading. "Reassess if it keeps losing" sounds reasonable but is hard to actually carry out. How much loss, for how long?
So before the paper trading started, I hardcoded the triggers and the decision order. The report has to tell apart three cases: a bug in the implementation, a strategy assumption that no longer holds, or plain normal volatility.
Triggers and the report
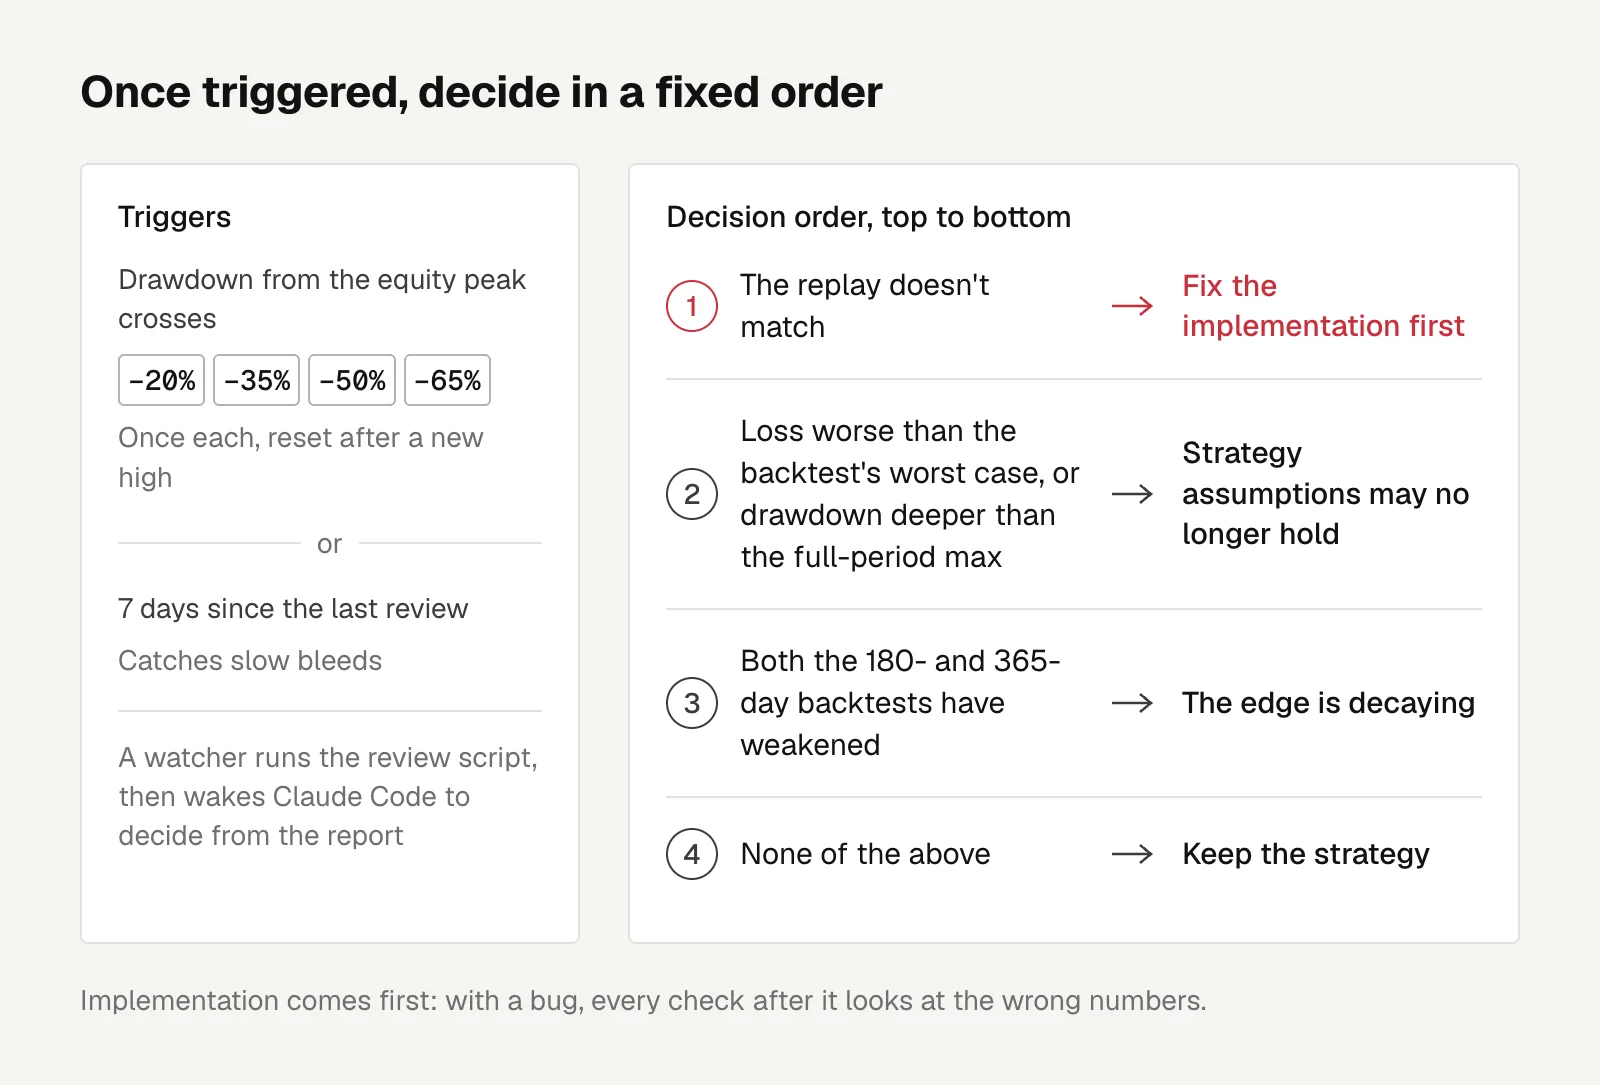
It fires once each time drawdown from the equity peak crosses −20%, −35%, −50%, and −65%, and the levels reset after a new high.
It also fires when 7 days have passed since the last review, to catch slow bleeds.
When a background watcher detects a trigger, it first runs the review script to produce a report, then wakes up Claude Code to make a call based on that report.
The most important part of the report is implementation consistency. Starting from the actual positions and cash at the candle where the live account opened, it replays the backtest. Then it compares, symbol by symbol, every position size, every rebalance, and the equity at every 4-hour close.
Position sizes carry no price noise, so they're the most precise consistency check.
Equity tolerance is max(2%, 1% × leverage), because live uses mark price (the exchange's reference price for unrealized P&L) while the backtest uses fill price, and leverage amplifies the gap.
The other three sections are P&L attribution, a historical comparison, and backtests over the last 30 to 365 days to see whether the edge is decaying. The historical comparison shows the distribution of returns and the worst case over the same length of time, following starts at 2.5x leverage or more.
Decision order: change the strategy or not?
- If the replay doesn't match, fix the implementation first.
- If the loss is worse than the backtest's worst case under the same conditions, or the drawdown is deeper than the full-period max drawdown, the strategy's assumptions may have stopped holding.
- If the backtests over both the last 180 and 365 days have weakened, the edge is decaying.
- If none of the above apply, keep the strategy.
Implementation comes first because when it has a bug, every check after it is looking at the wrong numbers.
The first trigger caught my own bugs
The day after the account opened, drawdown from the peak reached −20.3% and the watcher fired automatically.
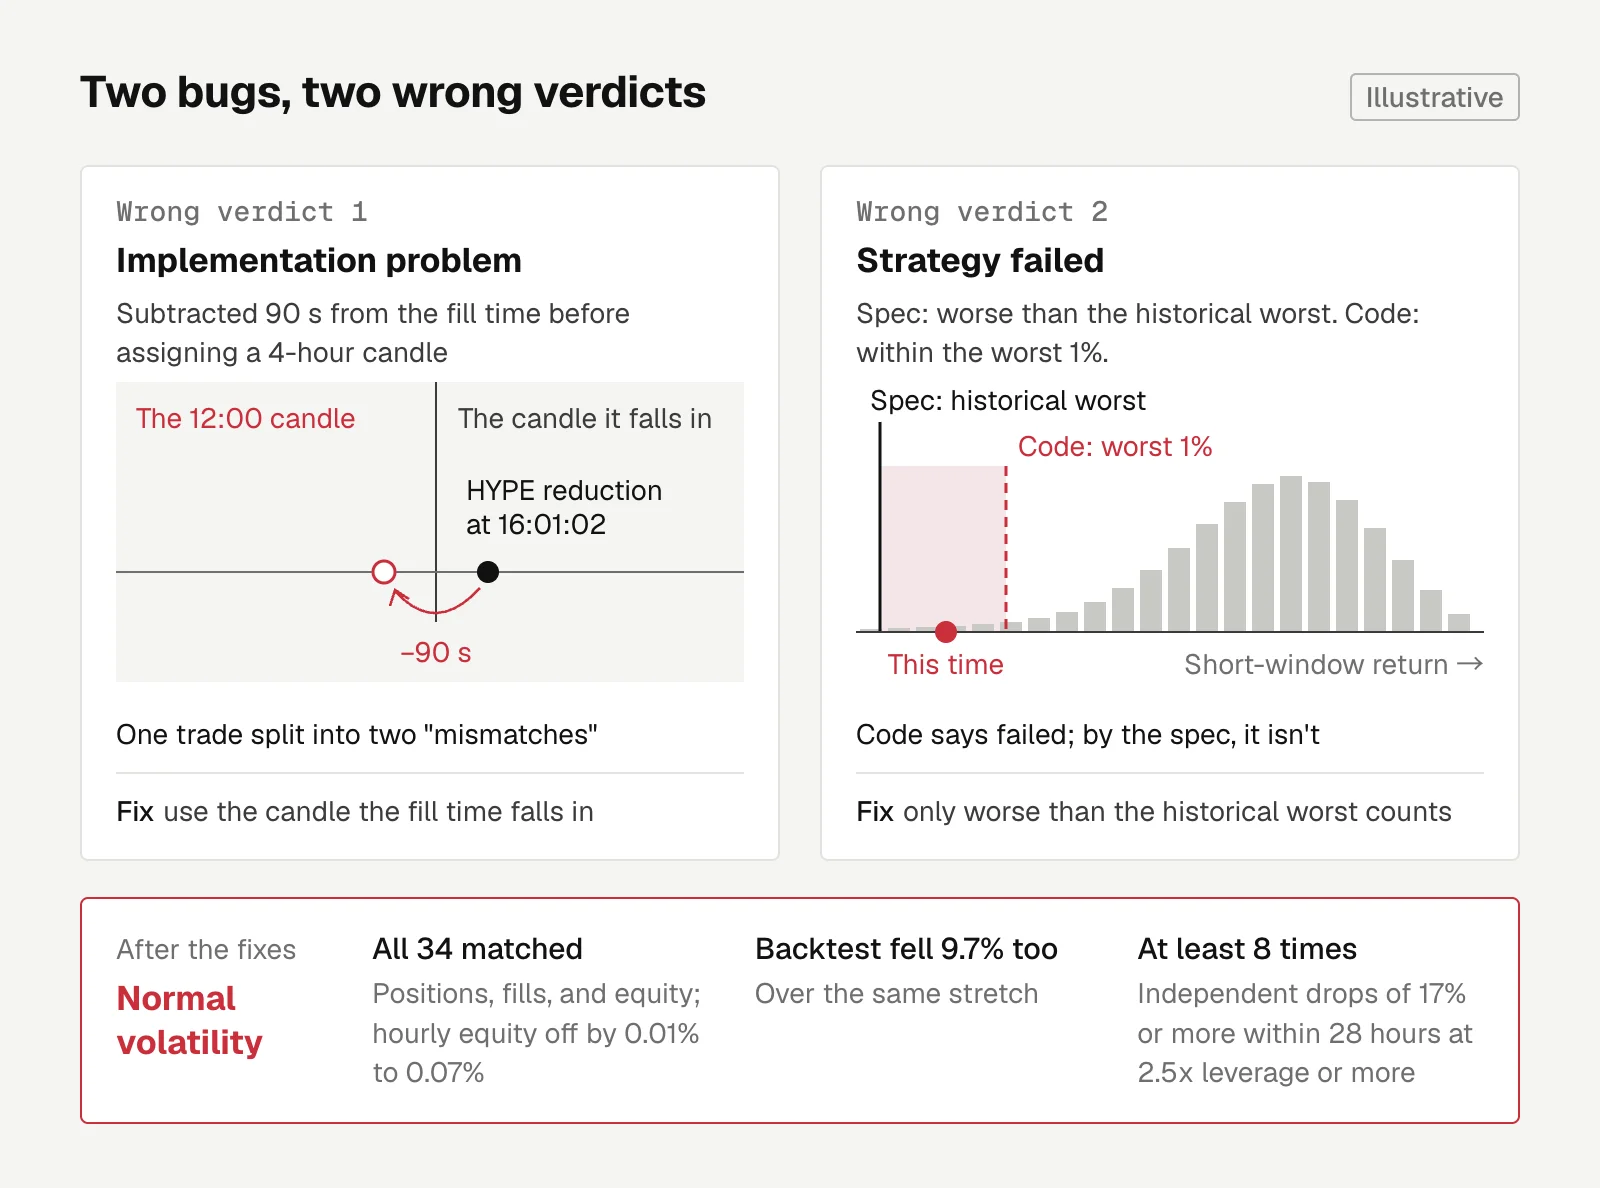
The first bug was in fill matching. The code subtracted 90 seconds from the live fill time before assigning it to a 4-hour candle, so a HYPE position reduction at 16:01:02 landed in the 12:00 candle.
One trade was split into two "mismatches," and the verdict was that the implementation had a problem. I changed it to use the candle the fill time actually falls in.
The second was in the decision condition. The spec said "worse than the historical worst case," but the code said "within the worst 1%," and the verdict was that the strategy had failed.
A 1st-percentile event over a short window is something that simply happens. The two conditions are far apart.
The spec and the code have to agree.
The review tool is itself code that needs testing. Of the two wrong verdicts, one claimed an implementation problem and one claimed strategy failure, and a wrong conclusion nearly drove the decision.
After the fixes, all 34 positions, fills, and equity matched, with hourly equity off by 0.01% to 0.07%. The backtest over the same stretch also fell 9.7%.
At 2.5x leverage or more, independent drops of 17% or more within 28 hours have happened at least 8 times historically. The unleveraged basket of positions fell only about 4.6%, and multiplying by roughly 3x gives this loss.
The verdict was normal volatility.
13 risk-reduction variants, none passed
The report also pointed out a structural problem: 34 highly correlated longs amount to one big bet in a crash.
The current weighting only controls each coin's volatility, not the portfolio's. In the backtest, at 2x leverage or more, the worst 28 hours came to −48.3%.
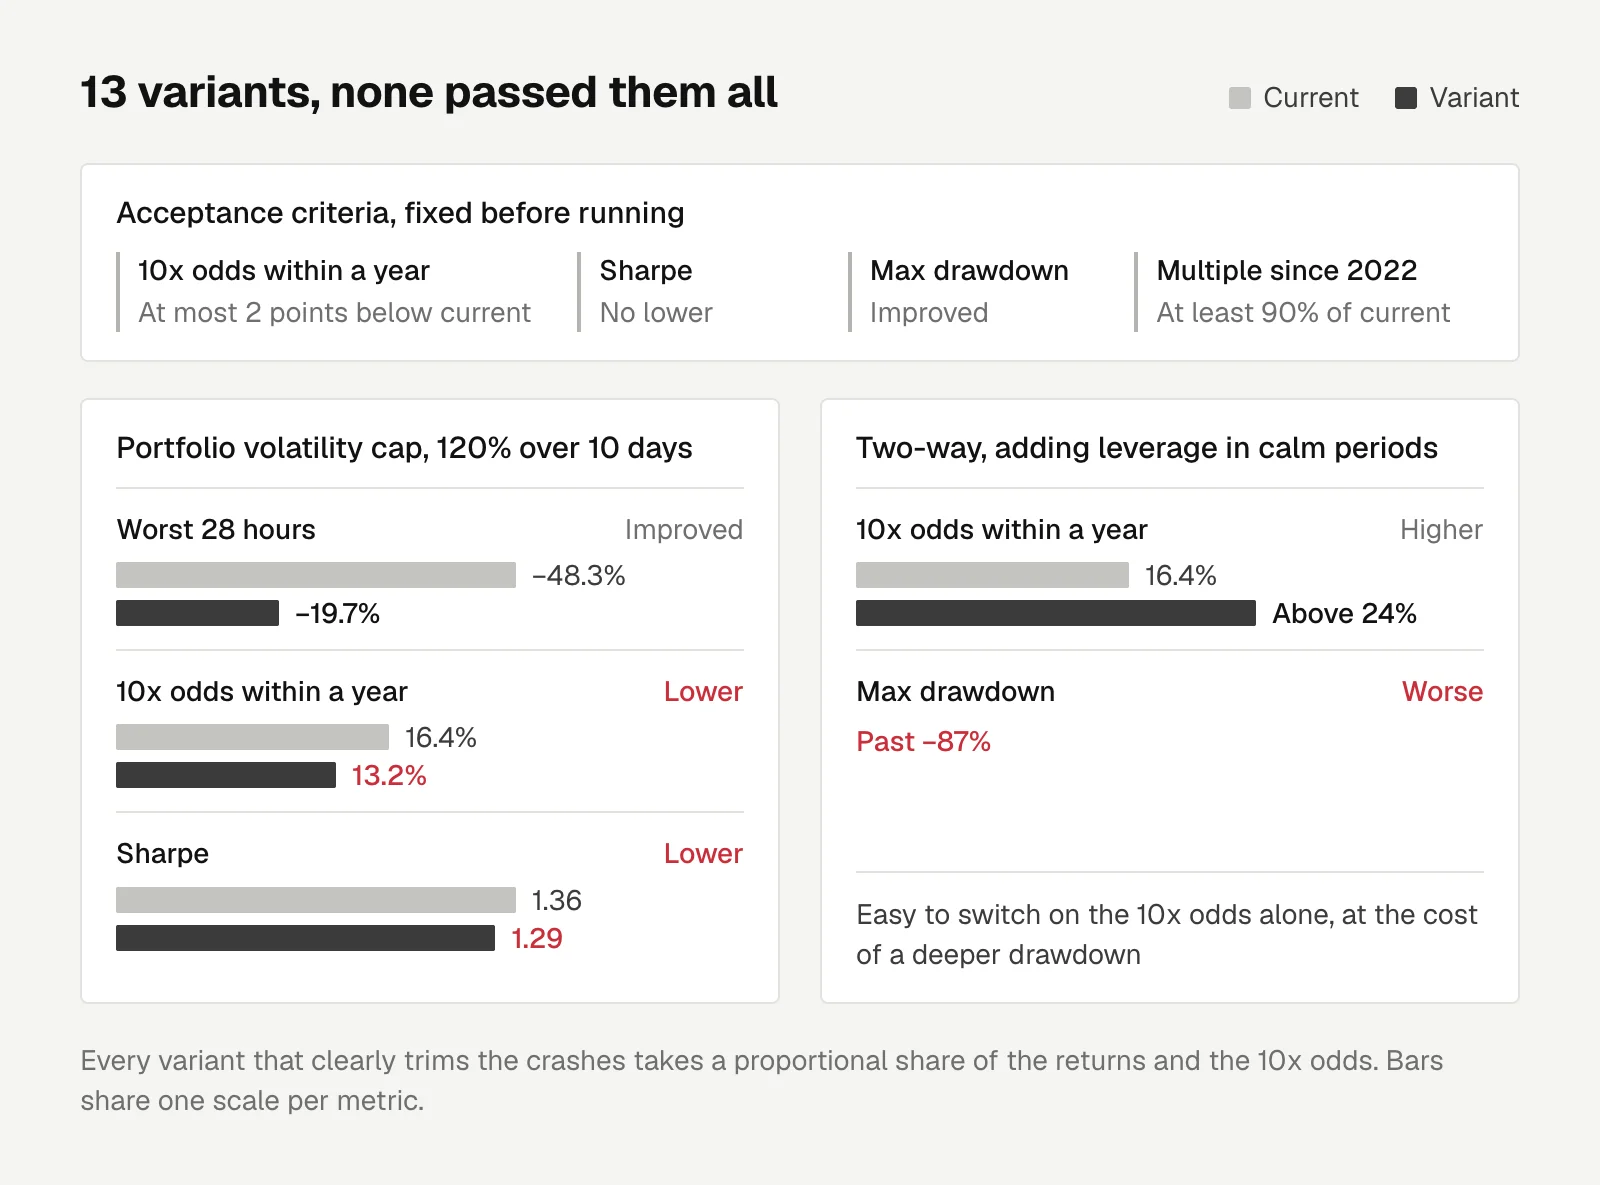
I tested 13 variants aimed at this, with acceptance criteria fixed before running them:
- The probability of 10x within a year no lower than the current one minus 2 percentage points
- Sharpe ratio no lower
- Max drawdown improved
- The multiple since 2022 at least 90% of the current one
None passed all of them.
A portfolio volatility cap of 120% over a 10-day window cut the worst 28 hours from −48.3% to −19.7%. But the 10x probability fell from 16.4% to 13.2%, and Sharpe from 1.36 to 1.29.
A two-way adjustment that also adds leverage in calm periods pushed the 10x probability above 24%, but max drawdown worsened past −87%.
So I changed nothing. The portfolio volatility cap is already tested and can be swapped in directly if I ever care more about safety.
The mechanism ended along with the project two days after going live, having run two reviews in total.
Set acceptance criteria first. Looking only at the 24% chance of 10x, it would have been easy to switch, at the cost of a −87% drawdown.
I haven't found a free way to cut tail risk. Every variant that clearly trims the crashes takes a proportional share of the returns and the 10x odds with it.
Investing
A Crypto Trend Strategy Backtested at 240x Lost 10.7% in 2.5 Days of Paper Trading: Survivorship Bias in the Coin List
A trend strategy that backtested at 240x lost 10.7% in 2.5 days live; a hindsight-picked coin list had inflated it, and with point-in-time rankings, 10x in a year only happened from a bull-market start.
Letters
Loading comments…