Investing · 2026.09.30 · 5 min · Updated 2026.10.26
A Crypto Trend Strategy Backtested at 240x Lost 10.7% in 2.5 Days of Paper Trading: Survivorship Bias in the Coin List
A trend strategy that backtested at 240x lost 10.7% in 2.5 days live; a hindsight-picked coin list had inflated it, and with point-in-time rankings, 10x in a year only happened from a bull-market start.
Reading
I set up a virtual account with 1,000 USDT and challenged myself to grow it to 10,000, using a crypto trend strategy that backtested at 240x.
In its first two and a half days of paper trading, it lost 10.7%.
The research I did right before ending it was the real point. The 35 symbols I used were picked after the fact, and about 65 percentage points of the backtest's annual return came from peeking at the future.
Switching to the top 35 by trading volume at the time, every case of reaching 10x within a year came from a 2020 start. Whether you can 10x comes down almost entirely to whether another big bull market shows up.
A ledger only fills, funding, and liquidations can touch
For the results to mean anything, I set two conditions. The strategy needs backtest evidence and has to honestly report its odds of 10x and its drawdowns. The paper ledger has to run on live market data with every cost accounted for.
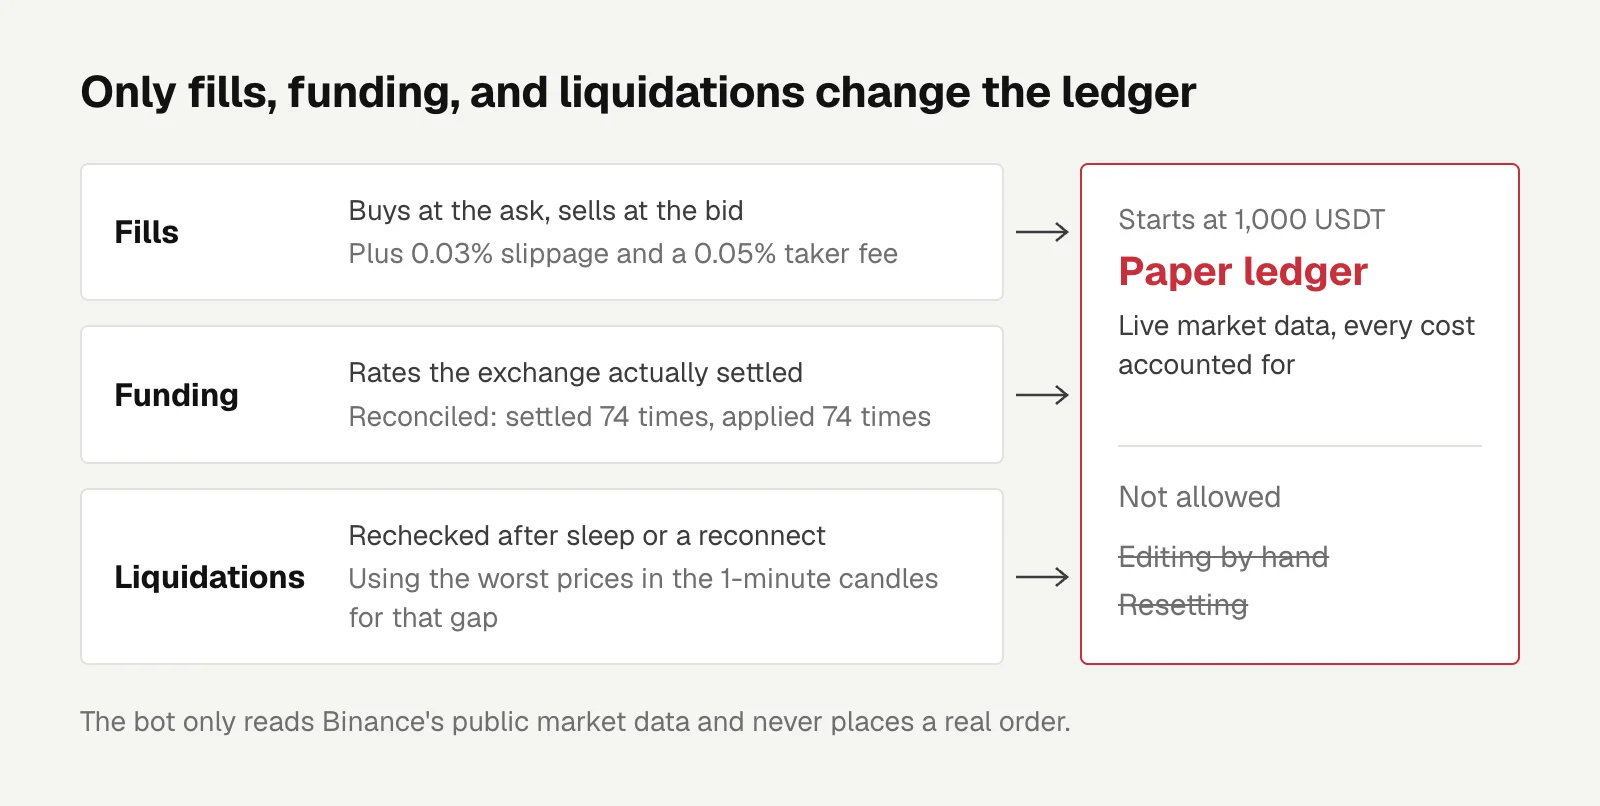
The ledger can't be edited by hand and never resets. Buys fill at the ask and sells at the bid, plus 0.03% slippage and a 0.05% taker fee.
Funding, the periodic payment between longs and shorts on perpetual contracts, uses the rates the exchange actually settled.
When the computer wakes from sleep or reconnects, it reruns liquidation checks using the worst prices in the 1-minute candles for that gap, so losses don't slip through just because nobody was watching. The bot only reads Binance's public market data and never places a real order.
I reconciled funding too. After the account opened, held symbols settled funding 74 times and the bot applied it 74 times. Some symbols settle every 4 hours and others every 8. Miss a detail like that and costs quietly go uncounted.
Funding is a heavy cost for long-only trend strategies, and backtests need actual historical rates.
A Donchian strategy that backtested at 240x
The data was 35 high-liquidity Binance USDT-M perpetual contracts: 1-hour candles from January 2020 plus the full funding history.
Comparing six signals at the same volatility target, a long-only daily Donchian 55/20 came out best, with a Sharpe ratio of 1.10.
I then adopted a few improvements: let winners run without trimming, add a BTC 200-day moving average filter, execute on 4-hour bars, and average the 20/10 and 55/20 sets.
Among the ideas I rejected, skipping longs when funding runs hot dropped the 10x probability to 3% to 10%, because the highest rates usually come during the steepest rallies. Shorting in bear markets got squeezed in 2025 and lost 46% to 61%.
The final live config was 4-hour candles, long only, volatility-weighted, with a target gross leverage of 3x and forced deleveraging above 3.5x.
Backtested from January 2020 to September 2026 with fees, slippage, and actual funding, it returned 240x: 125% annualized, Sharpe 1.38, max drawdown −73%. From any start date, the probability of hitting 10x within 1 year was 16.4%, and within 2 years 27.6%.
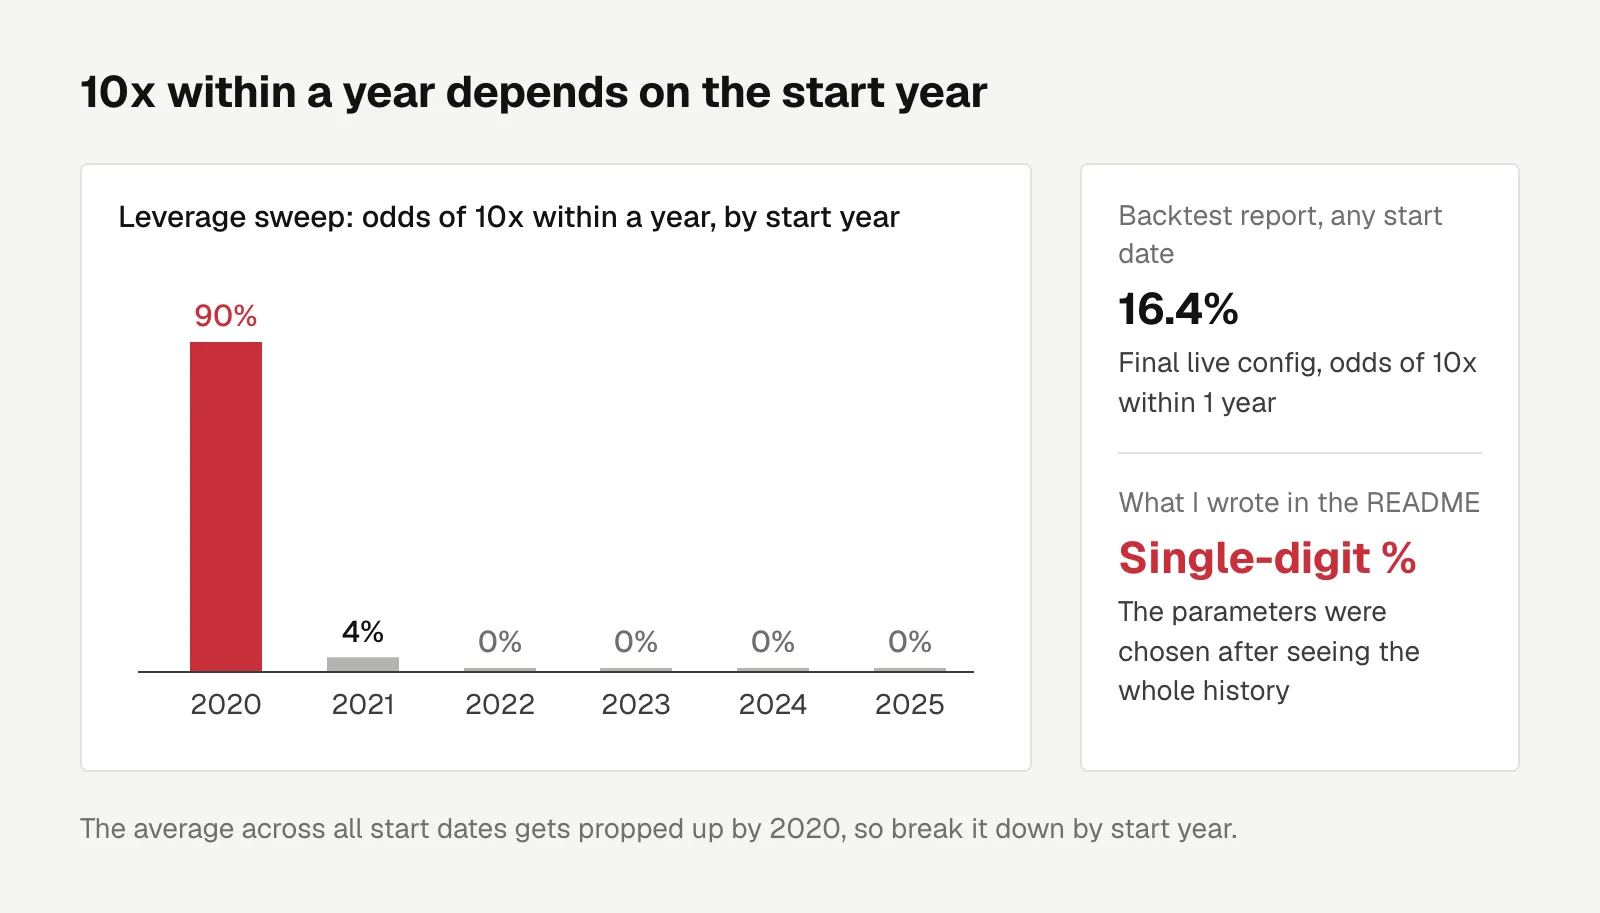
The warning signs were there early. In the leverage sweep, the probability of 10x within a year was 90% from a 2020 start, 4% from 2021, and 0% from every start in 2022 through 2025.
The parameters had also been chosen after seeing the whole history, so the expectation I actually wrote in the README was a single-digit percent chance of 10x within a year.
Down 10.7% in two and a half days
At open, going by the signal on the latest 4-hour candle, it opened longs on 34 symbols for a total exposure of 2.92x.
On day two, drawdown from the peak crossed −20% and triggered the loss review I had written in advance. The verdict: the implementation was fine, the loss was within historical range, keep the strategy. The review mechanism is covered in coding the loss review for a quant trading strategy.
When I stopped, equity was at −10.7%, after a high of +3.9% and a low of about −17.9%.
The account opened right at the tail end of a big rally. The backtest showed the strategy had gained about 70% in the 30 days before open, and right after going fully invested it ran into a market-wide pullback.
Those two and a half days also showed something the backtest report hadn't made clear: an average annualized volatility of 86% understates the risk at high leverage.
On days when the prior day's leverage was 2.5x or more, the standard deviation of daily returns was 10%, about 190% annualized. A 10% move in a day was normal.
A fixed 35 is hindsight
I picked my 35 in 2026, so every one of them is a coin that survived to today and grew. That's survivorship bias in the coin list.
If you instead use only the top 35 by volume on each day (point-in-time), comparing on the daily version:
| Daily version, 2020 to now | Fixed 35 | Top 35 by volume at the time |
|---|---|---|
| Annualized return | 101% | 36% |
| Sharpe | 1.26 | 0.80 |
After 2023 the point-in-time version returns only 1.2x.
Re-running the leverage sweep on the point-in-time universe, long-run growth peaks at a volatility target of 1.5 to 2.0. The 2.5 I used was trading growth for a better shot at 10x.
The median outcome after holding for one year was 0.86x to 0.90x. Every case of 10x within a year came from a 2020 start (79%). Starts from 2021 through 2025 were all 0%.
The odds of 10x depend heavily on the market phase you start in. The average across all start dates gets propped up by 2020, so break it down by start year.
That same day I dropped the 10x goal and ended the project. None of the code, market data, or ledger was kept.
Engineering
Publishing a Chrome Extension to the Chrome Web Store, Plus a Cross-Platform One-Line Install Script
Getting Auto Approve for Muse through Chrome Web Store review, and a one-line install script for macOS, Linux, and Windows that keeps the steps to a minimum, since Chrome won't let programs install extensions.
Letters
Loading comments…