Investing · 2026.09.27 · 5 min · Updated 2026.10.26
QQQ or SPY? Why I Dollar-Cost Average Everything Into QQQ on IBKR, and the Drawdown I Accept
Why I dropped my 30% drawdown cap and now dollar-cost average monthly into QQQ on IBKR, covering the QQQ vs SPY history, the drawdown I accept, my rules for crashes, and long-term costs.
Reading
QQQ or SPY for a monthly US ETF plan? I ended up dollar-cost averaging on IBKR every month, all of it into QQQ, with no drawdown limit.
Since its 1999 launch QQQ has returned 10.9% a year, ahead of SPY's 8.6%, and it wins most rolling 10-year windows.
The price is a -83% max drawdown that took almost 15 years to get back to the previous high.
So the rules have to be written down first: keep buying through drops, don't sell, don't add leverage, don't borrow.
Moving to IBKR, dropping the drawdown budget
After backtesting market timing against buy and hold, my first allocation was 00631L (a 2x leveraged Taiwan 50 ETF), 0050 (the plain Taiwan 50 ETF), and cash, keeping max drawdown within 30%.
That allocation lasted four days.
I moved to IBKR as my broker and buy US stocks directly, which saves one currency conversion. One deposit and one order a month is all it takes.
The biggest change was how I think about drawdowns.
The 30% drawdown budget was something I set for myself, and looking back, what it held down was long-term return.
I plan to leave this money alone for 10 years or more. What I really need to protect is that I keep buying and don't sell in a crash. How deep the paper drawdown goes is secondary.
QQQ vs SPY
I compared QQQ against VOO. VOO tracks the same index as SPY, and SPY has a longer history, so I used SPY in its place. The data starts at QQQ's launch in 1999:
| QQQ | SPY | |
|---|---|---|
| Annualized return | 10.9% | 8.6% |
| Max drawdown | -83% (2000 to 2002) | -55% (2008) |
| Time back to the prior high | 14.9 years | 4.9 years |
| 2022 decline | -35% | -24% |
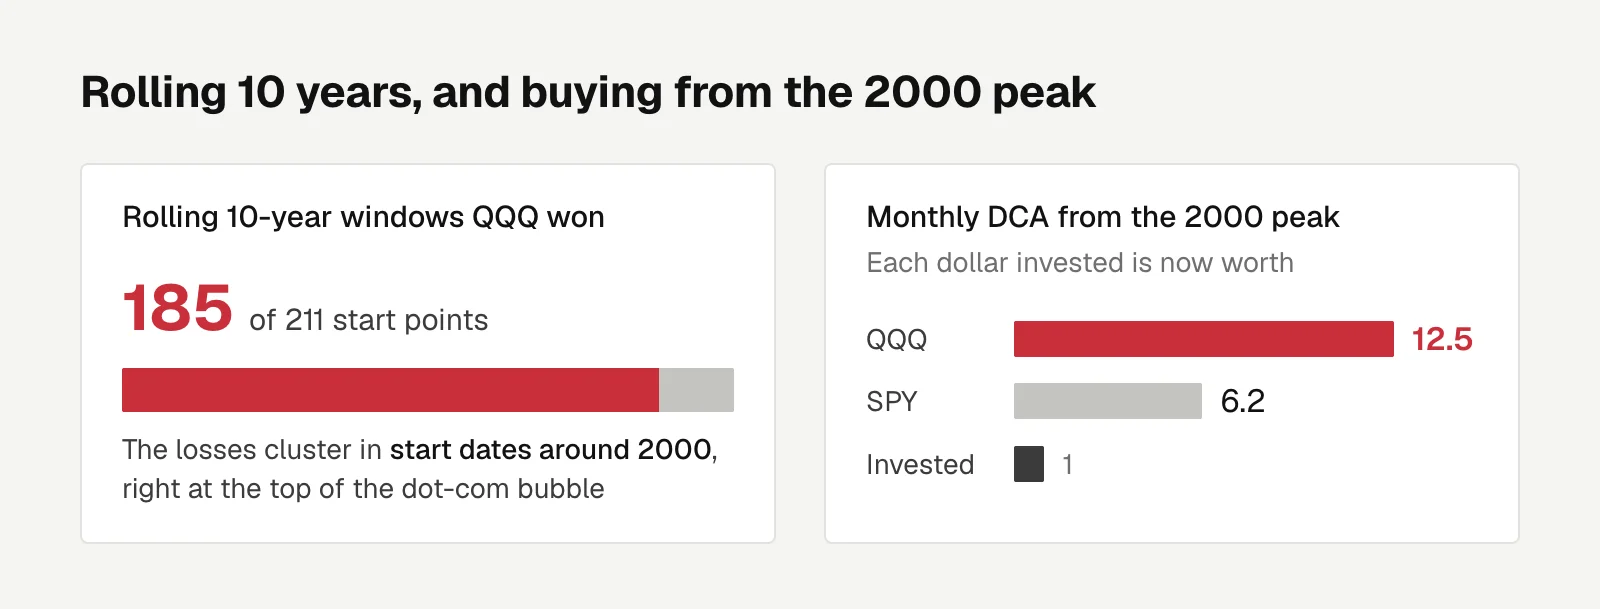
Over rolling 10-year windows, QQQ won 185 of 211 starting points. The losses cluster in start dates around 2000, in other words buying right at the top of the dot-com bubble.
Even with that kind of bad luck, dollar-cost averaging every month from the 2000 peak until now turns each dollar invested into 12.5 with QQQ and 6.2 with SPY.
QQQM tracks the same index as QQQ. After QQQ converted to an open-end fund, its expense ratio dropped to 0.18%, while QQQM's is 0.15%, a difference of only 0.03% a year.
IBKR lets you buy fractional shares, so QQQ at over US$700 a share isn't a problem. I chose QQQ, and it's the only thing I buy.
Drawdown is the price, so set rules first
Dropping the drawdown limit rests on three conditions: this money stays put for 10 years or more, living expenses are set aside separately, and I keep buying when it falls.
If I can't hold to any one of them, going all in on QQQ isn't right for me.
When it falls, I follow the plan. Down 30%, keep buying. Down 50%, keep buying. No selling. No added leverage, so no QLD or TQQQ. No borrowing to buy more.
It counts as done once I've kept contributing through a decline of 30% or more without pausing or selling.
Expected returns need a conservative view too. From 2015 to 2026 QQQ returned about 19% a year, most of it from P/E expansion, so for planning I assume 5% to 8% nominal.
Two allocations I didn't use
An outlook research report I put together recommended 60% VOO, 25% QQQM, and 15% 0050.
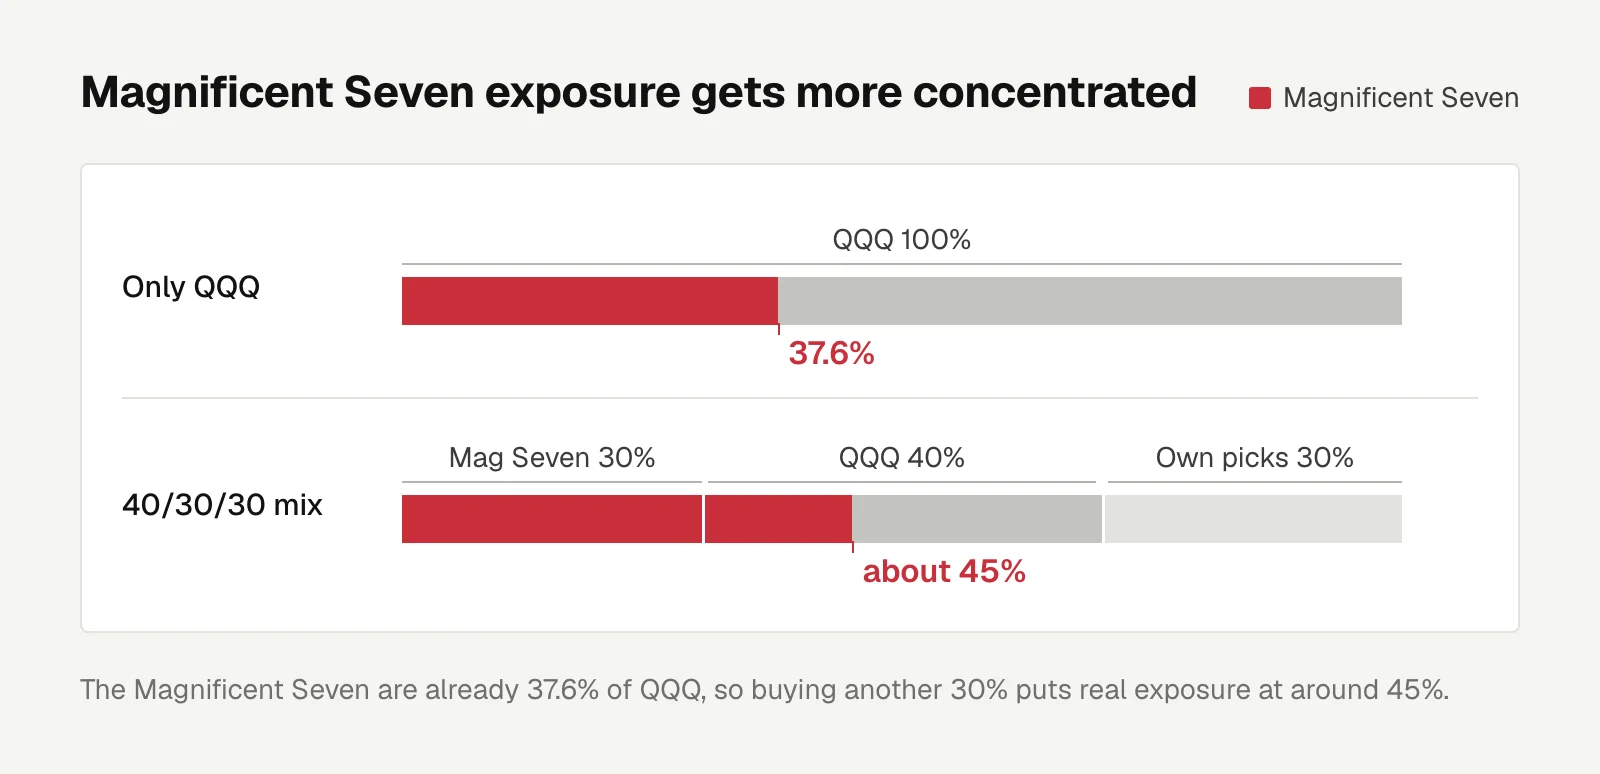
The reasoning: QQQ's earnings yield is now below the 10-year US Treasury yield, the Magnificent Seven make up 37.6% of it, and institutions' 10-year forecasts for US growth stocks are low.
But those weights were worked out under the 30% drawdown cap, a premise I've dropped. Institutional forecasts are also often wrong; from 2014 to 2024 they kept underestimating US stocks.
Another allocation I hear a lot is 40% QQQ, 30% Magnificent Seven, and 30% individual picks, taking out a personal loan to buy more in a bear market.
The Magnificent Seven are already inside QQQ, so this puts real exposure to them at around 45%, more concentrated than buying only QQQ.
And you'd be carrying a loan through the bear market. That's hard to hold on through.
Long-term costs: withholding and estate tax
US-listed ETFs carry two structural costs for non-US persons, and you feel them more the longer you hold:
- 30% dividend withholding: QQQ yields about 0.44%, so that's a drag of roughly 0.13 percentage points a year
- US estate tax: non-US persons with US assets above US$60,000 have to file Form 706-NA on the excess, at rates of 18% to 40%
The IRS states the withholding rule plainly:
Most types of U.S. source income received by a foreign person are subject to U.S. tax of 30%.
That's from the IRS page on NRA withholding, and dividends that US ETFs pay to non-US persons fall under it.
The usual way to handle estate tax is to buy an Ireland-domiciled UCITS ETF that tracks the Nasdaq-100. I haven't verified specific products or fees yet.
While putting this together I also briefly used QQQ's old expense ratio. Broker rules and fees change fast, so now I always check the official announcements first.
This decision is based on my own situation and isn't investment advice. If you might need the money within 10 years, or your emergency fund isn't ready yet, going all in on QQQ probably isn't for you.
Investing
Market Timing vs Buy and Hold: Backtests Across Taiwan and US Stocks, Futures, and Crypto, and None Beat Holding
I backtested timing and quant strategies across Taiwan stocks, US stocks, futures, and crypto, and after costs and daily-equity drawdowns none beat holding, while raising monthly contributions actually worked.
Letters
Loading comments…